
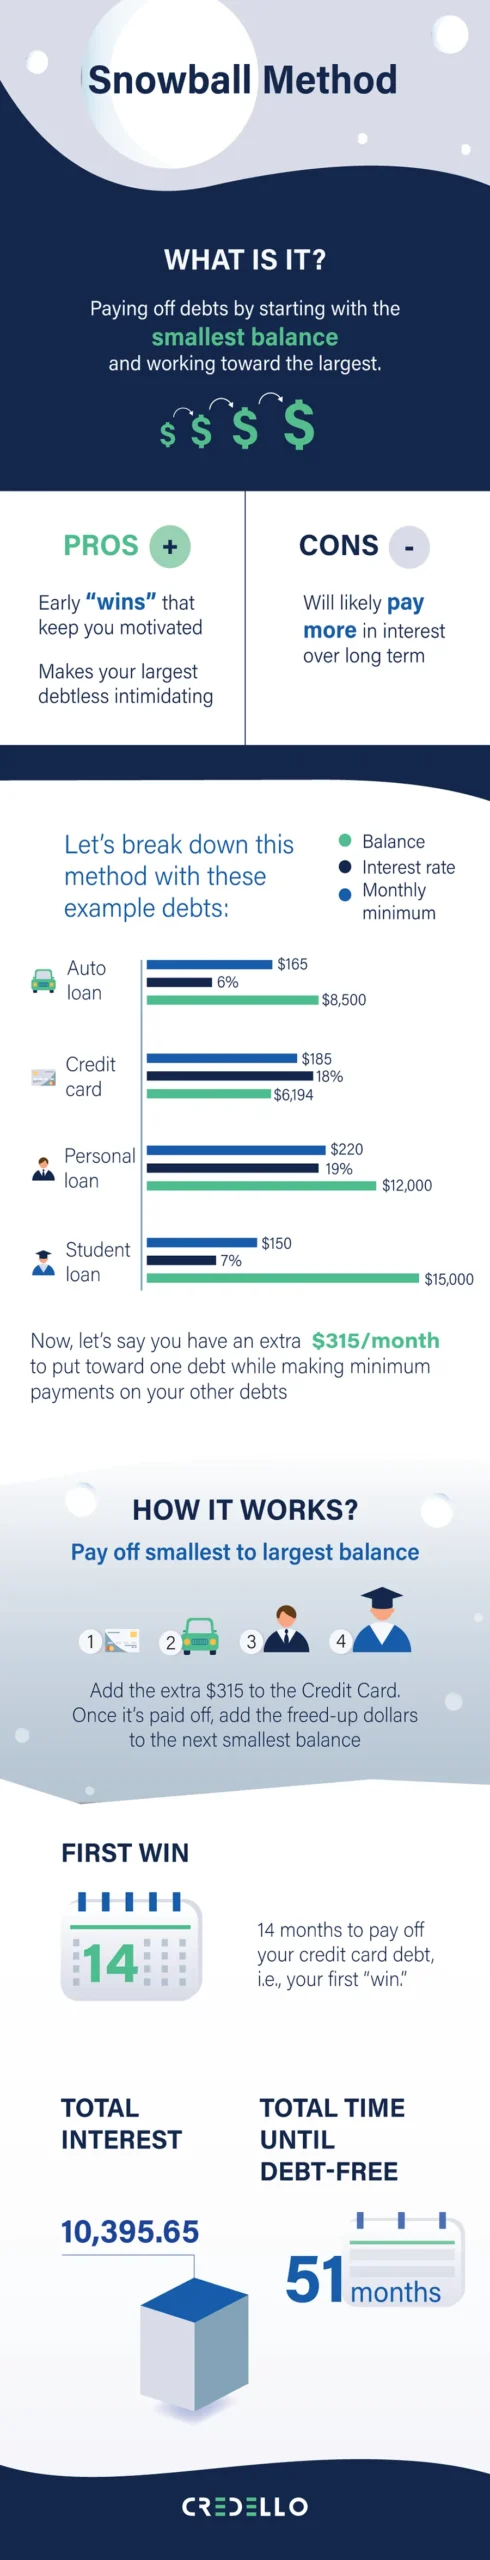
Another client sat across my desk last Friday at 4:45 PM, sliding a stack of past-due collection notices across the wood. Six credit cards, two personal loans, and a car note. They were drowning in minimum payments, paying hundreds in interest every month, and completely paralyzed by the sheer volume of red ink. They wanted a complex, multi-tiered algorithmic debt consolidation matrix. I told them to throw it in the shredder.
We mapped out a raw, unvarnished debt snowball right there on a yellow legal pad. Not because it makes the prettiest spreadsheet on Wall Street, but because human psychology dictates that behavior modification beats raw interest-rate math every single time. If you need a sterile, academic paper on amortization schedules, look elsewhere. Here is how you actually execute the debt snowball method without burning out.
- List all debts from smallest balance to largest, ignoring interest rates entirely.
- Attack the smallest balance with aggressive, laser-focused monthly cash flow.
- Roll every single freed-up dollar into the next target until the ledger is clean.
The Cold Math vs. Human Behavior Reality Check
Financial purists love to scream about the debt avalanche method—paying off high-interest debt first to save a few bucks in interest over three years. Sounds great on paper. In reality? Most people who use the avalanche method quit within 90 days because staring down a $14,000 personal loan feels like climbing Everest in flip-flops. You lose steam. You get discouraged.
The debt snowball method weaponizes quick wins. When you wipe out a $400 department store balance in month one, your brain releases dopamine. You see the needle move. That momentum is worth more than saving forty bucks in cumulative interest charges over two years. Here is a realistic field breakdown of how a typical four-debt portfolio looks when we restructure it for a client:
| Debt Item | Balance | Interest Rate | Min Payment |
|---|---|---|---|
| Store Card | $350 | 24.99% | $35 |
| Visa Card | $2,400 | 18.99% | $75 |
| Car Note | $9,200 | 7.50% | $280 |
| Personal Loan | $14,500 | 12.50% | $310 |
Notice that the highest interest rate is actually on the smallest balance, which is a common scenario. But even if the store card was at 10% and the personal loan at 29%, the snowball order remains strictly locked by balance size, not percentage.
Executing the Snowball: Step-by-Step Execution
Big mistake. Don’t start paying extra on everything simultaneously. That spreads your ammunition too thin and accomplishes nothing. You must concentrate your firepower like artillery.
Step 1: Freeze the Bleeding
Cut up the plastic. Unlink the cards from Amazon, Uber, and your grocery delivery apps. If you keep swiping while trying to climb out of a hole, you are bailing water out of a boat with a screen door. Stop adding new consumer debt immediately.
Step 2: Rank Strictly by Balance
Ignore the interest rates. Write down every unsecured debt you own from the smallest total payoff amount to the largest total payoff amount. Sum up your mandatory minimum payments so you know your baseline survival cost every month.
Step 3: Hunt Down Gazelle Intensity Cash Flow
Your baseline income is likely already spoken for by rent, utilities, and groceries. To accelerate the debt snowball method, you need temporary lifestyle sacrifice. Sell the bass boat. Pick up weekend delivery shifts. Cut the dining-out budget to absolute zero for six months. This isn’t forever; it’s a financial rescue mission.
Step 4: Roll the Snowball
Put every single extra dollar you claw back from your budget—plus any extra cash from side hustles—onto that smallest balance. Once that first balance hits zero, take its minimum payment ($35) and add it directly to the minimum payment of the second debt ($75). Now you are pounding the second debt with $110 plus whatever extra cash you generated. The snowball grows heavier, faster, and more destructive with every scalp you collect.
📊 Real-World Monthly Payment & True Cost Calculator
LIVE INTERACTIVE UTILITYCommon Obstacles and How to Push Through Them
Inevitably, life punches you in the mouth around month four. Your transmission blows up, or your HVAC unit drops dead in July. This is why we always advise keeping a starter emergency fund of $1,000 before you launch full throttle into your snowball. Do not drain your last dollar to pay off a credit card only to run up a brand-new emergency room bill on a high-interest card because you had zero cash reserves.
If an unexpected expense drains your buffer, pause the extra snowball payments temporarily, rebuild the $1,000 buffer in thirty days, and slam your foot right back on the gas pedal. Do not quit just because of a speed bump. Consistency beats perfection every single time.
Frequently Asked Questions
Does the debt snowball method actually work better than math-based methods?
Yes, behavioral psychology consistently beats spreadsheet logic. By knocking out smaller balances first, you secure quick psychological wins that keep you motivated to finish the plan.
Should I include my mortgage in the debt snowball?
No. Never include your primary mortgage in a debt snowball. Focus strictly on unsecured consumer debt like credit cards, personal loans, and car notes.
What happens when I pay off my first small debt?
You take the exact payment amount you were using for that debt and roll it directly into the minimum payment of the next smallest debt, creating a compounding effect.
